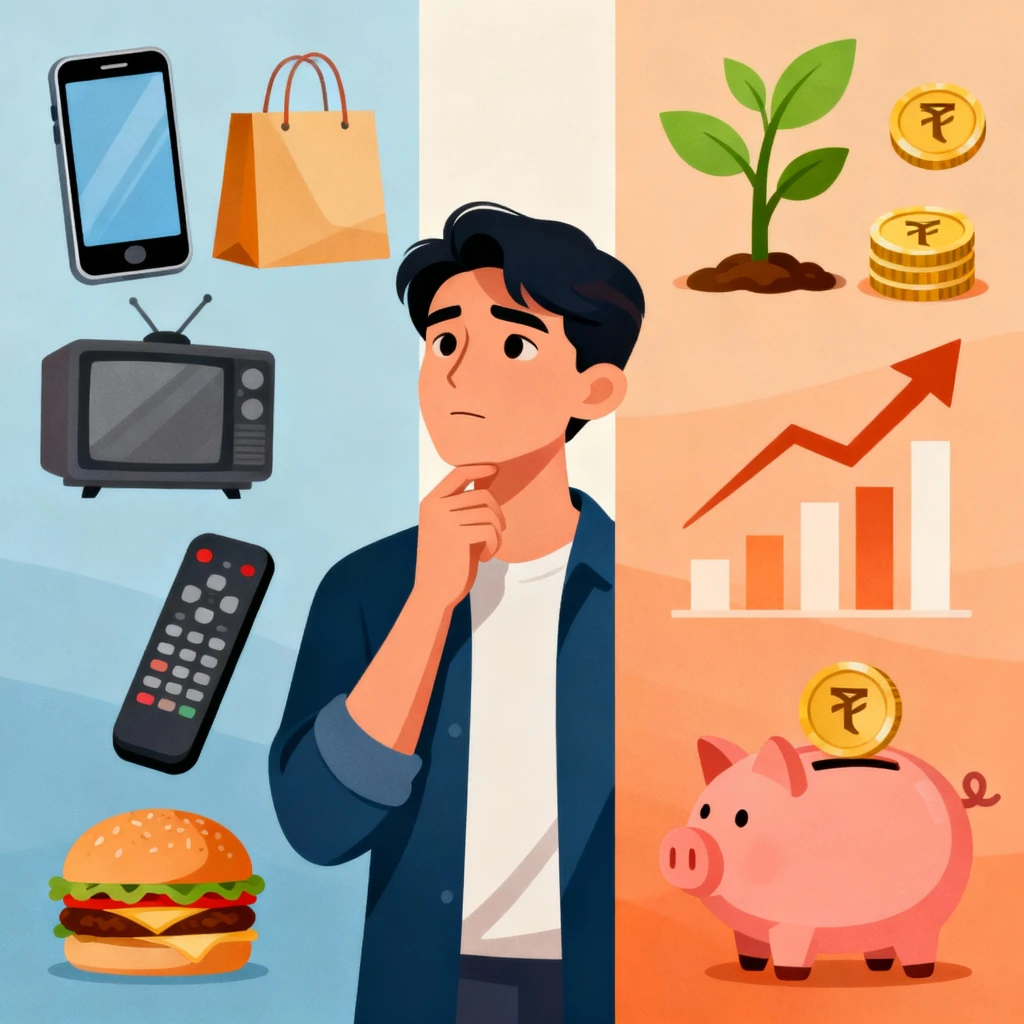
Many investors know the value of starting early, yet they hesitate. They wait for markets to cool, for bonuses to arrive, or for “a better time.” The reason is not always poor planning but psychology. Present bias, the tendency to favour immediate rewards over future benefits, plays a powerful role in financial decision-making. It is one of the biggest invisible barriers to building long-term wealth.
Breakdown
Context:
Present bias explains why saving, investing, or exercising discipline feels harder than it should. Even when individuals recognise the benefits of compounding or disciplined investing, the comfort of spending now often wins. Behavioural economists describe this as a mismatch between intention and action. The result is delayed investment and missed opportunities for growth.
Angles:
This bias is particularly visible in retail investing. Many people keep money idle in savings accounts, waiting for the “right time” to enter the market. Ironically, data repeatedly shows that time in the market matters far more than timing the market. Early investors benefit from compounding returns, while procrastinators lose valuable years of potential growth. Financial advisors are increasingly focusing on behavioural coaching, not just asset allocation, to address this gap.
What’s Next:
Experts suggest structured investing habits as a remedy. Systematic Investment Plans (SIPs), auto-debit options, and goal-linked investments help override impulsive choices by removing the need for repeated decision-making. The next phase of financial advisory will likely blend behavioural insights with digital automation to build discipline into investing.
Why This Matters
Understanding present bias is key to improving financial well-being. It explains why even well-informed investors struggle to act on their goals. Recognising this bias allows individuals to design systems that protect them from their own instincts and ensure that long-term goals are not derailed by short-term emotions.
The Big Picture
Money decisions are rarely about numbers alone. They are about psychology, habits, and trade-offs between today and tomorrow. As financial literacy deepens in India, the next evolution of investing will depend on how effectively individuals manage behavioural patterns that undermine consistency. Present bias is not a flaw to eliminate but a tendency to understand and plan around.
The Crunch
The perfect time to invest does not exist, but the cost of waiting always does. Every delayed decision carries an opportunity cost that compounds quietly over time. The investors who win are not those with perfect timing but those who overcome hesitation and let time work in their favour.