Market Roundup
Indian equities ended marginally lower for a seventh straight session ahead of Wednesday’s RBI decision. The Sensex closed at 80,364.94 and the Nifty 50 at 24,634.90, slipping in late trade on continued foreign outflows and pressure in IT and autos. Safe havens stayed in demand with gold and silver at record levels in India. The rupee hovered near an all time low on persistent dollar demand.
Sentiment: Cautious risk off into policy week.
Domestic Factors: RBI MPC begins deliberations with a possible twenty five basis point cut on the table. Moody’s retains India at Baa3 with a stable outlook. EV charging push under PM E DRIVE signals infra acceleration.
Global Factors: Record bullion on global safe haven bid and a softer dollar. Persistent trade and tariff uncertainties shaping sector moves. Global rate path in focus ahead of key data.
Market Snapshot – At a Glance
| Indicator | Status |
|---|---|
| Opening Trend | Flat to mild positive, faded by close. |
| Nifty Close | 24,634.90. |
| Sensex Close | 80,364.94. |
| FII Activity | Net sell ₹2,831.6 crore. DIIs net buy ₹3,845.9 crore. |
| Investor Sentiment | Defensive, preference for energy and OMCs, IT and autos soft. |
| Domestic Catalyst | RBI policy, EV charging guidelines, semicon capex. |
| Global Backdrop | Strong bullion, weak rupee, trade policy overhang. |
| Gold (per 10 grams) | ~₹1,19,500 at record territory today. |
| Silver (per kg) | ~₹1,50,000 record high. |
What Moved Today
RBI policy preview and cut debate
The MPC meeting began today with the decision due Wednesday. A section of the street expects a twenty five basis point “booster cut” as inflation cools, while others see a hold with a dovish tilt. Markets are positioned cautiously after a seven day slide and ongoing FII outflows. Expect sensitivity in banks, NBFCs, real estate, and rate sensitive autos into the print.
Moody’s holds India at Baa3, stable
Moody’s retained India’s sovereign rating at Baa3 with a stable outlook. The affirmation underscores resilient growth prospects and institutional strength, even as external risks and fiscal metrics remain watch points. This anchors global investor perception ahead of RBI and supports medium term capital flows if macro stability persists.
UST and Kaynes Semicon to build ₹3,330 crore OSAT in Gujarat
A joint venture will set up an assembly and test facility in Sanand, tightening India’s links in the chip value chain. The partnership pairs a global client network with domestic manufacturing depth and digital engineering. Execution will be judged on yield, uptime, and anchor customers, but the signal on semicon manufacturing is unambiguous.
EV charging push under PM E DRIVE
Operational guidelines target about 72,300 public chargers with a ₹2,000 crore outlay, including full subsidy for government premises with free public access. The move standardises deployment, improves accessibility, and attacks range anxiety. Watch utilities, charge point operators, DISCOM coordination, and urban local bodies for rollout pace.
GIFT City momentum with caveats
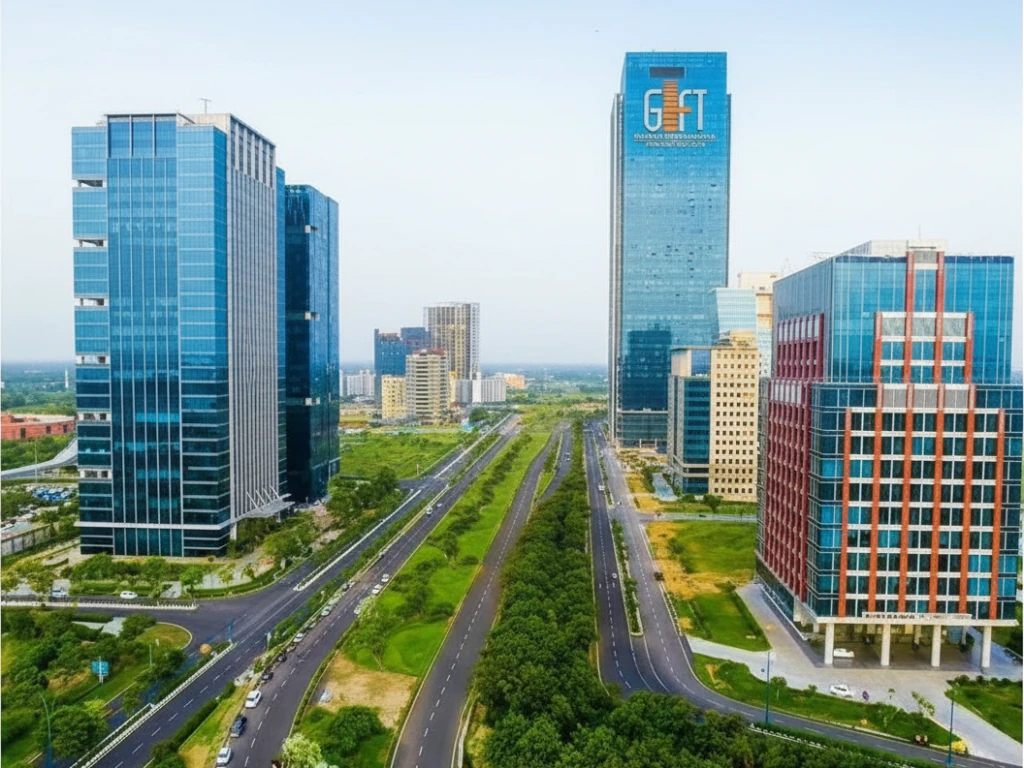
A PwC survey flags rising interest in IFSC GIFT City on tax and regulatory advantages, yet notes gaps in brand visibility, talent depth, and ecosystem scale relative to London and Singapore. The next leg requires anchor mandates, stronger talent pipelines, and deeper capital market breadth.
AI trust crisis and the PPP playbook
The World Economic Forum spotlights a four point eight trillion dollar upside at risk without trustworthy AI. Only sixty two percent of leaders believe AI is used responsibly. Public private partnerships can translate principles into audits, registries, and incident reporting to scale safe adoption.
In Focus
- Generative AI’s contrarian view. A critique argues that if frontier AI proves less economically decisive than hyped, the outcome could still be positive by reducing systemic risk and concentration.
- Global Sustainability Alliance 2025. Policymakers, industry, and global leaders align on partnerships to scale climate positive projects.
- RBI appoints S. C. Murmu as Deputy Governor. A personnel move that shapes policy execution and supervisory focus.
- India–Europe FTA from October one, per commerce minister remarks, and parallel updates on talks with other partners. Trade architecture may pivot export sectors and supply chains.
- Homegrown apps in the spotlight. Zoho’s Arattai reports a hundred times traffic surge and adoption by senior ministers, reflecting the self reliance shift in consumer and enterprise messaging.
Other Stories
- Rupee near record low as outflows persist; RBI said to manage volatility through banks. One line weaker bias into policy week.
- Gold and silver futures hit fresh records on global cues and soft dollar. One line bullion bid continues.
- Markets opened firm but ended marginally lower ahead of RBI; volatility remained elevated. One line energy outperformed, FMCG lagged.
- X to appeal Indian court order on content removal. One line platform regulation risk remains live.
- Volkswagen to overhaul India business amid market pressures. One line product and cost reset in focus.
- Bhutan’s KHPL signs ₹4,829 crore loan pact with PFC. One line hydro link strengthens India Bhutan power corridor.
- JLR to resume some manufacturing sections in coming days. One line supply chain normalisation.
- NCH logs three thousand GST related complaints after tax cuts. One line compliance push to ensure consumer pass through.
Read more at makhanamornings.in
Why This Matters
Today’s mix is classic policy week. A likely dovish RBI against record bullion, a weak rupee, and measured sovereign affirmation keeps India’s macro anchor intact while acknowledging risk. Capex stories in semiconductors and EV charging show the state market partnership model at work, converting policy into assets and networks. GIFT City’s survey read reminds us that incentives start the flywheel but credibility and talent sustain it. The AI trust theme is not just a technology story. It is a governance and inclusion question that decides whether productivity gains spread or concentrate. For operators and investors the signal is to balance defense and offense. Manage currency and rate risk tightly, but lean into real economy buildouts where regulatory clarity and public support shorten time to scale.
The Bigger Picture
India’s near term market wobble sits alongside long duration structural moves. Domestic demand remains resilient, but transmission from policy to corporate earnings will be uneven across sectors and time. The rupee near lows and bullion at highs reflect a global risk premium that India does not fully control, yet credible institutions and steady sovereign views help cushion shocks. The build out of EV infrastructure and the shift from chip design to assembly and test are examples of knitting supply chains at home while plugging into global networks. Trade architecture with Europe and others can widen that aperture if execution stays consistent. The long game is depth. Depth in talent, depth in capital, depth in governance. If India compounds these with targeted reforms and interoperable standards, the economy can convert cautious cycles into durable, inclusive growth.
That’s your roundup for today. Stay sharp, stay curious, and keep moving smarter.
AD | Makhana Mornings
PS: If you enjoyed today’s edition, share it with a friend who wants to stay ahead of the curve. A sharper morning is better when it is shared.