For years, term insurance premiums carried an 18 percent GST, pushing many middle-class Indians to skip or delay buying adequate coverage. That changes now.
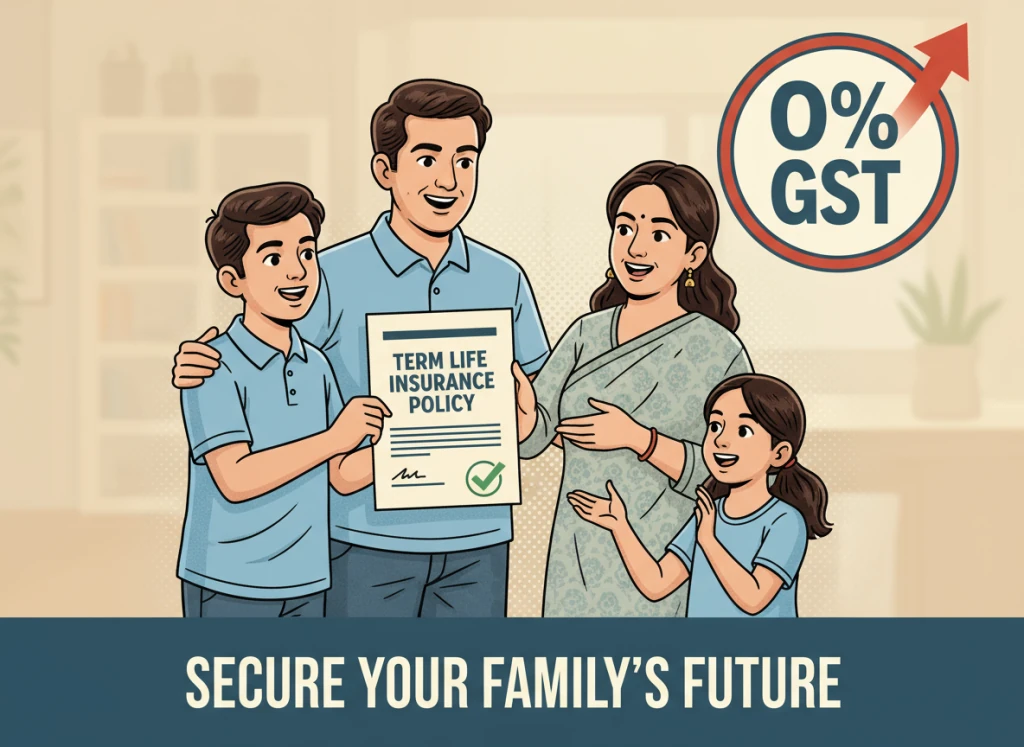
Under the new GST 2.0 reforms, effective from 22 September 2025, the government has announced a 0 percent GST rate on term insurance. The move is being hailed as one of the most consumer-friendly reforms under the new GST regime and one that directly impacts affordability, financial inclusion, and protection coverage.
Breakdown
Context:
The earlier 18 percent GST on pure term plans made them costlier than endowment or ULIP products. For instance, a premium of ₹20,000 per year included ₹3,600 in taxes, which was a clear deterrent for price-sensitive consumers.
Angles:
The shift to 0 percent GST aligns with the government’s push for wider insurance penetration, which currently stands below 4 percent of GDP. It also reflects the broader GST 2.0 agenda focused on simplifying tax slabs, reducing consumer-facing taxes, and improving compliance. Insurers are expected to pass the benefit directly to customers, leading to an immediate drop in premiums.
What’s Next:
Industry experts expect a 15 to 18 percent increase in new policy enrollments over the next year, especially among first-time buyers aged 25 to 40. Insurance platforms and fintech players are preparing promotional campaigns around the reform to capture this new demand.
Why This Matters
This reform not only makes protection more accessible but also signals a shift in policy priorities from revenue collection to risk coverage. For millions of Indians who delayed insurance purchases due to cost, this removes a major psychological and financial barrier. It could also encourage stronger competition among insurers as margins narrow and customer acquisition accelerates.
The Big Picture
GST 2.0 is shaping up to be more than a tax reform. It represents a behavioral shift. By reducing the cost of essential financial products, it aims to expand India’s financial safety net. If implemented effectively, it can help India move closer to the goal of “insurance for all” while supporting growth in the financial services sector.
The Crunch
The biggest advantage will go to those who act early. With premiums likely to stabilize before insurers revise their pricing models, early policyholders can secure lower rates for the long term. For startups in fintech, insurtech, and financial advisory, this is the right time to focus on awareness, bundling, and distribution strategies that make insurance as mainstream as digital payments.